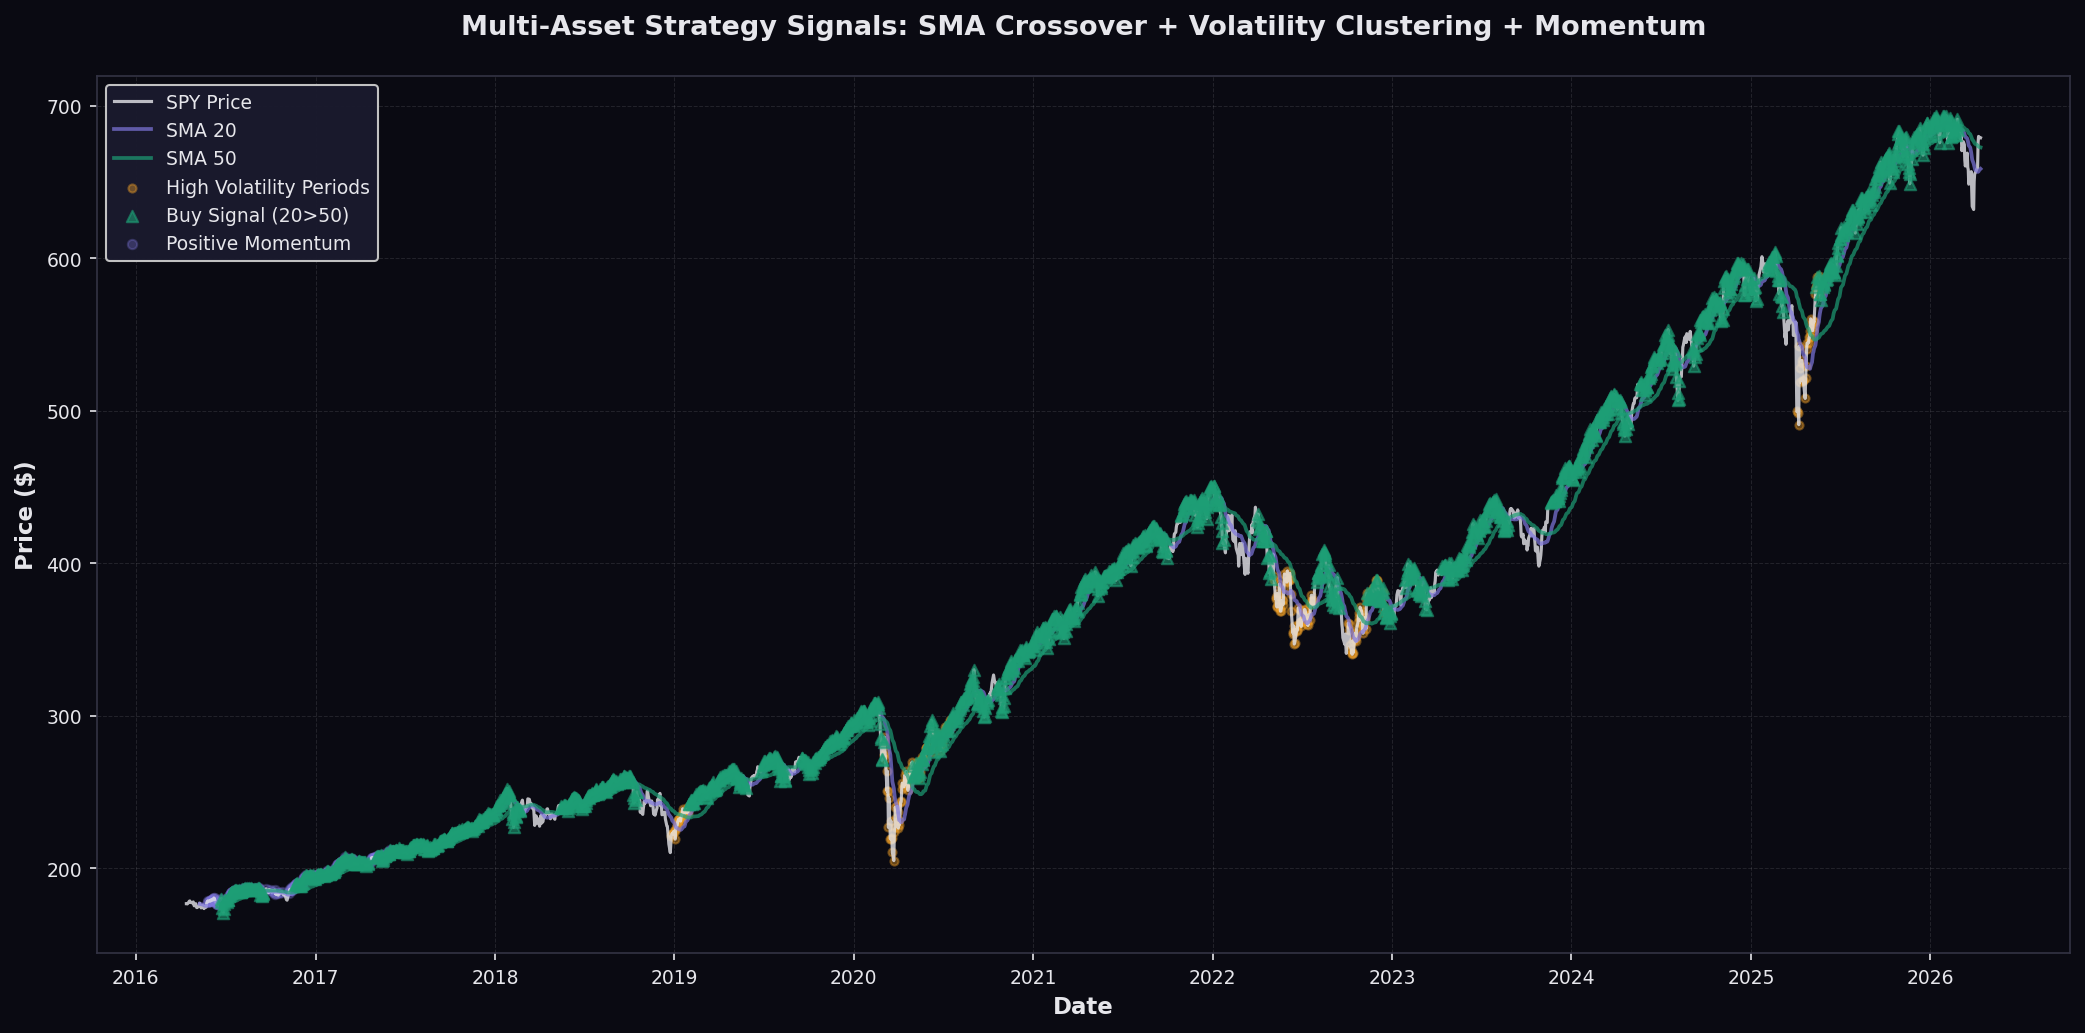
Standard Geometric Brownian Motion assumes constant volatility and normally distributed returns — a clean mathematical convenience that real markets routinely violate. In practice, large price moves c
Markdown supported · ⌘↵ to post
No responses yet.